Moving insurance: what is covered?
Protection when moving
Moving insurance: statutory liability and extra protection
What applies, what is missing
What is often called “moving insurance” is first of all the moving company's statutory liability under the German Commercial Code (HGB). It applies to every removal contract, whether a private move or a commercial move: if belongings are lost or damaged, the company is liable for up to €620 per cubic metre of loading space required for your move (§ 451e HGB). For 30 m³ that is a maximum of €18,600. What is reimbursed is the value at the place and time of acceptance, i.e. the current value.
Certain cases are excluded, such as money, jewellery and documents, or damage caused by your own inadequate packing (§ 451d HGB). The same limit also applies to long-distance moves – so anyone taking valuable furniture, art or a piano along should consider additional insurance. At Beste Umzug Unternehmen we discuss this before the move and give you the fixed price after the survey.
Clarify liability before you set off
Liability under the HGB, additional insurance on request
Call us on 01625978461 with no obligation. We explain how far the statutory liability goes for your volume and discuss whether additional insurance makes sense for individual items. We give you the fixed price after the survey; we are based in Berlin and drive nationwide.
Offers available individually, depending on effort, scheduling and the scope of services required.
How we handle liability and damage
Inform beforehand, settle cleanly afterwards
The law requires moving companies to inform consumers clearly and prominently, when the contract is concluded, about liability and the option of further insurance (§ 451g HGB). That is exactly what we do: you find out in advance what liability under the HGB covers and what it does not. On request we document the condition of your furniture before transport and settle claims in line with the statutory deadlines – for a private move just as for a long-distance move.
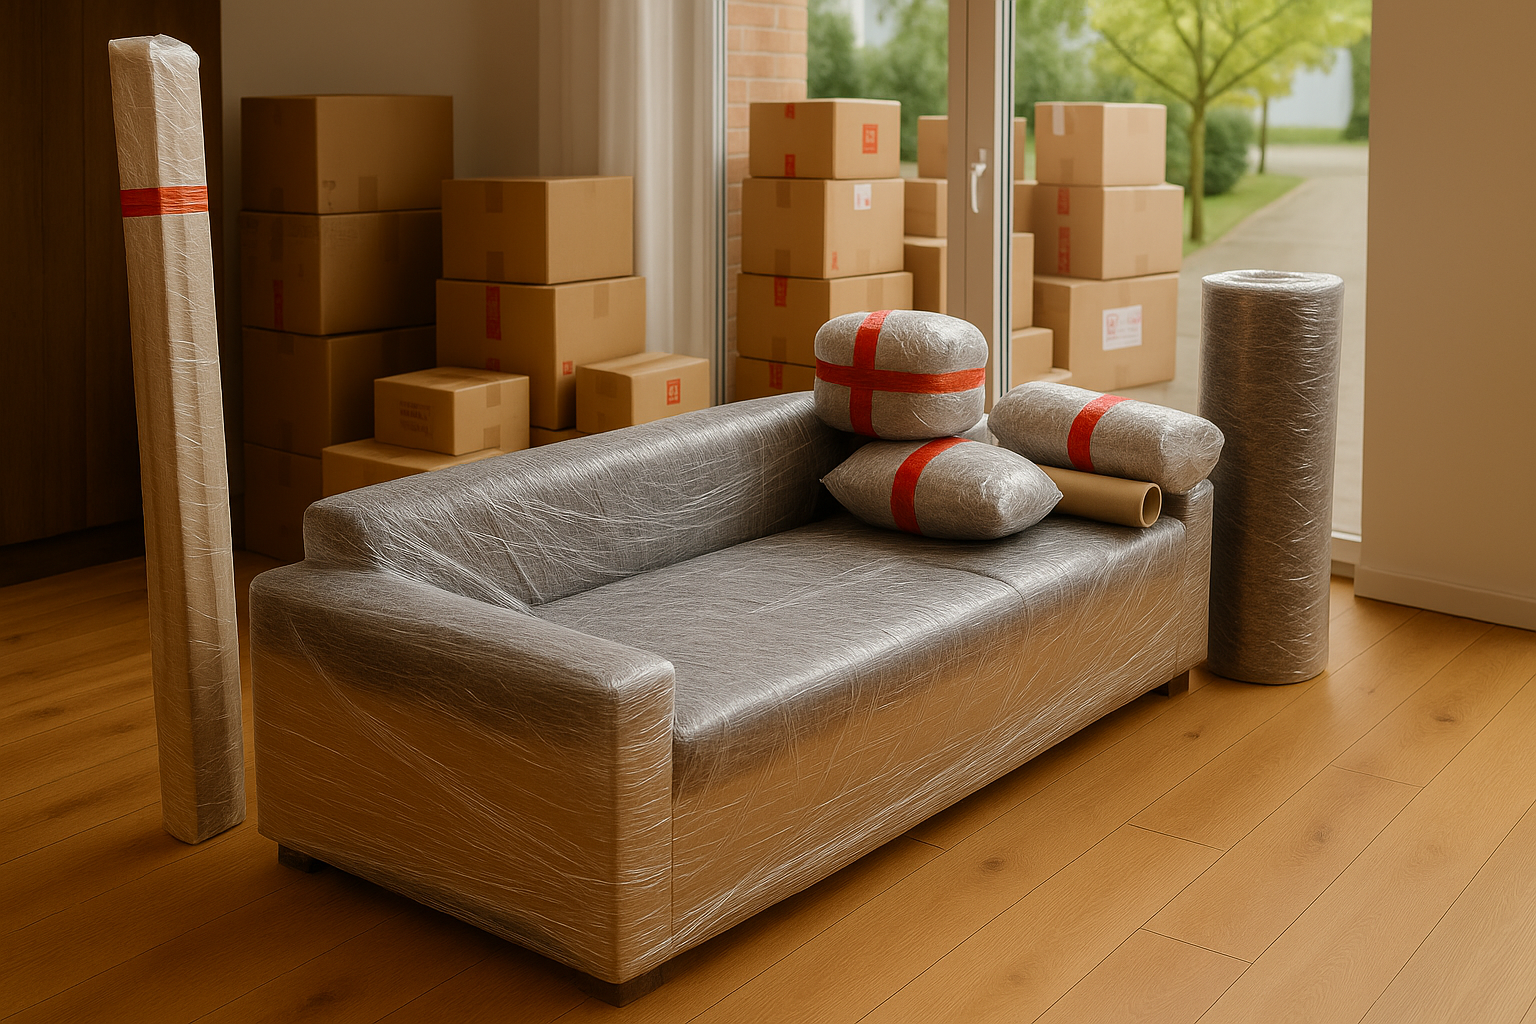
Packing service
Condition report
Valuables separately
Furniture transport
What you should know about your protection
Statutory liability is based on the loading space, not on the value of your furniture. An inventory list with values quickly shows whether individual items exceed the limit and should be insured additionally.
Liability per cubic metre
Current value, not new price
Clear exclusions
Know the deadlines
Report in writing
Extra protection possible
Part load: the same liability
With a part load, several customers share one transport. Your belongings are nevertheless subject to the full statutory liability of €620 per cubic metre of the loading space your things need. For 5 m³ that is up to €3,100 – so you should additionally protect valuable individual items.
Liability,
contents insurance, claims
There are several levels to moving insurance: the moving company's liability under the HGB, optional transport insurance and your contents insurance, which during transport only steps in for the risks insured there, such as fire or burglary. Distinguishing from existing damage is also important. How to report damage correctly is explained in the article Claiming for moving damage; special features of long-distance moves can be found there.
Before the move
Packing and liability
After the damage
Frequently asked questions on liability when moving
What damage does moving insurance cover?
Covered are loss of and damage to the belongings in the period from acceptance to delivery – i.e. during loading, the journey and unloading, if the company carries out this work. Liability is limited to €620 per cubic metre of loading space required (§ 451e HGB); the value at the time of acceptance is reimbursed (§ 429 HGB). Damage to walls, stairwells or door frames is not damage to goods; the company is liable for it under general law if its team caused the damage.
Under § 451d HGB, excluded items include precious metals, jewellery, money, securities and documents, damage caused by inadequate packing or labelling by the customer, items loaded by the customer themselves, live animals and plants, and damage arising from the particular fragility of an item. At Beste Umzug Unternehmen we pack fragile items ourselves on request, so that this exclusion does not apply.
How is a claim settled?
It is best to record visible damage directly on delivery – it must be reported no later than the day after. Hidden damage that you only notice when unpacking must be reported within 14 days of delivery (§ 451f HGB). After delivery, the report must be in text form; an email with photos and a short description is enough.
We then examine the damage and settle it – depending on the case, by repair or compensation for the value within the statutory liability. Missed deadlines cause the claim to lapse, unless the company failed to inform you on delivery about the form and deadline for reporting damage (§ 451g HGB). So keep the quote, inventory list and photos until the matter is settled.
Prices for your protected move
With us there are no hidden costs. The price scale is based on the number of rooms: 1-room flats from €349, 2-room flats from €615, 3-room flats from €894 and 4-room flats from €1,344. For houses or villas we always draw up an individual quote, as the scope varies greatly. Anyone moving over a greater distance should calculate from €3.80/km for the long-distance move. At the free survey we also clarify whether additional insurance makes sense for individual items.
What determines the price – and the liability limit
First of all, the volume plays a central role – it also determines the statutory liability limit of €620 per m³. Next comes the distance, which starts at €3.80/km. Further factors are the floor, the lift and a possible no-parking zone. For additional services we recommend furniture assembly and a part load.
Services that prevent damage
These services reduce the risk of damage even before transport.
- 📦 Furniture transport: safe furniture transport with special packaging.
- 🏠 Private move: an individual private move to suit your wishes.
- 🏢 Company relocation: a smooth company relocation without a long interruption to business.
- 🚚 Part load: an inexpensive part load for smaller volumes.
- 🔧 Move with assembly: a complete move with assembly from a single source.
- 🧹 House clearance: fast house clearance including disposal.
The same liability on every route
Whether within Berlin or right across Germany: liability under the HGB is the same for every move. We are based in Berlin and drive nationwide – destinations can be found in the overview of destinations, long distances under Long-distance moves.
Related Articles
Packing alongside your job: a packing plan for the evenings before the move